The following article by Habhajan Singh is related to his previous article which I posted in this blog. There seems to be some differences in method of implementation but I wonder whether the financial commitments of purchaser and financier are any different.
http://islamicfinanceasia.blogspot.com/
Monday, December 8, 2008
RHB Islamic phases out ‘disputed’ BBA financing
By HABHAJAN SINGH
RHB Islamic Bank Bhd has completely phased out Al-Bai Bithaman Ajil (BBA) in favour of the musharakah mutanaqisah concept for its home financing products. This probably makes it one of the first local Islamic subsidiaries of local banks to move away completely from BBA which has been under increasing scrutiny over the years.
The move by RHB Islamic, one of the 17 Islamic banks including Al Rajhi Banking & Investment Corporation (Malaysia) Bhd and Maybank Islamic Bhd licensed by Bank Negara Malaysia (BNM), signals a shift in the local Islamic home financing front away from BBA.
"RHB Islamic has taken a stance of phasing out products and services based on BBA or bai al-inah with effect Oct 1. This is based on (its) Shariah committee's advice to adopt globally accepted Shariah principles," RHB Islamic Head of Shariah Division Ahmad Suhaimi Yahya told The Malaysian Reserve.
He added that the move is in tandem with the bank’s strategy to position itself as the banker of choice for local and international customers looking for Shariah-compliant financial products and services. This is in reference to the fact that BBA, with underlying concepts of bai dayn (debt trading) and bai inah (sale with imediate repurchase), are shunned in jurisdictions like the Middle East and Pakistan. BBA, which may involve the two concepts, is a deferred sale contract for a sale price that includes the profit, with a repayment period agreed beforehand.
For so many years, local Islamic banks have made BBA the linchpin when carving out Islamic financing, which now stands around RM143.4 billion.
The Islamic banking assets, according to latest statistics from the central bank, have expanded by 23% to RM234.9 billion compared to a year ago. The Islamic banking industry now accounts for 16.7% of total assets in the industry. It is understood that other banks are also in the midst of preparing to put on the shelf more home financing offerings that are not based on BBA contracts.
The recent major trigger for the move away from BBA was the July 18 written judgment by High Court judge Justice Datuk Abdul Wahab Patail in Arab-Malaysian Finance Bhd vs Taman Ihsan Jaya, first reported by The Malaysian Reserve on Sept 8.
The judgment, a collective ruling on 12 cases now pending an appeal, sent shockwaves in the local Islamic banking fraternity as they began deciphering its impact.
For starters, the judge had ruled that the application of the BBA contracts in those cases were contrary to the Islamic Banking Act 1983 (IBA). The judge ruled that since some BBA contracts were structurally faulty, defaulters need not pay more than the original financing amount that they received, depriving banks of the profit they would have otherwise booked from the transaction.
Bankers fear that this judgement could mean that current BBA financing clients would only need to pay the facility amount and would escape from paying the profit portion.
Following the High Court ruling, BNM sent a circular dated Sept 8 to heads of Islamic financial institutions to "strongly advise" them to review their heavy reliance on the BBA concept in their transactions.
The circular noted the industry's seeming over dependence on BBA, adding that BBA is a Shariah concept introduced more than 20 years ago to facililtate growth and development of Islamic finance.
At its end, RHB Islamic is offering Equity Home Financing-i to its customers based on diminishing musharakah or musharakah mutanaqisah as an alternative to the earlier BBA home financing.
Thursday, December 11, 2008


Thursday, December 4, 2008
EPF is affected by the Stock Market too
This article in The Star shows that performance of EPF's investment is affected by the ups and downs of the stock market too. Thus the return that EPF can provide for its members can be affected by the performance of the stock market. This is because the EPF invests quite substantially in the stock market.
Risks due to investment in the stock market is substantially reduced if the amount that is allowed to be withdrawn from the EPF is invested in a well managed unit trust fund. It has been shown in the past that the performance of a good unit trust fund has always exceeded that of the EPF over the long term.
Thursday December 4, 2008
EPF Q3 income dips 60%
By YVONNE TAN
PETALING JAYA: The Employees Provident Fund’s (EPF) total investment income for the third quarter (Q3) fell 60.4% to RM2.06bil from RM5.2bil in the previous quarter (Q2) as its investments, especially equities, were affected by the global economic uncertainty.
The EPF said in a statement yesterday income from equities in the June to September period fell by more than half to RM1.26bil from RM2.54bil in the preceding quarter.
In line with accounting best practices and as a conservative provisioning policy, the EPF also made allowances amounting to RM2.29bil for diminution in the value of equity investments due to the deterioration in market value compared with RM416.7mil in Q2.
“The outlook in the fourth quarter is likely to reflect the full-scale impact of the global meltdown, although there is still hope for the Malaysian equity market to bounce back,” chief executive officer Datuk Azlan Zainol said yesterday.
Azlan believed Malaysia’s competitive edge would help sustain the economy during these difficult times.
The EPF said due to the current global economic uncertainty, stock markets across the globe had fallen significantly, including the local equity market.
Bursa Malaysia’s market capitalisation during Q3 shrank by about RM200bil to RM770bil.
In the same period, the KL Composite Index fell 243.81 points, or 19.3%, to 1,018.68.
On the investment income of RM2.06bil in Q3, the EPF said it was predominantly driven by Malaysian government securities (MGS) and loans and bonds.
In the quarter under review, the EPF received 3.1% higher returns from loans and bonds, raising income to RM1.71bil which was an increase of 3.14% or RM52.05mil from Q2’s RM1.66bil.
Its investment income in MGS rose 1.38% to RM1.217bil against the preceding quarter’s RM1.2bil.
EPF said the most of Q3 investments were in the trade and services sector and the finance sector comprising 38% and 33.9% of total equity investments respectively.
The next largest Q3 equity investment was in the plantations sector, representing 8.5% of total equity investments.
Money market instruments provided an income of RM142.25mil, down 49.21% from RM191.46mil in Q2.
Investments in properties yielded returns of RM21.53mil, down from RM22.66mil in Q2.
“The EPF will always maintain a policy of low-risk investment decisions. As a national premier pension fund, we cannot afford to take on high risk investments,” Azlan said.
Risks due to investment in the stock market is substantially reduced if the amount that is allowed to be withdrawn from the EPF is invested in a well managed unit trust fund. It has been shown in the past that the performance of a good unit trust fund has always exceeded that of the EPF over the long term.
Thursday December 4, 2008
EPF Q3 income dips 60%
By YVONNE TAN
PETALING JAYA: The Employees Provident Fund’s (EPF) total investment income for the third quarter (Q3) fell 60.4% to RM2.06bil from RM5.2bil in the previous quarter (Q2) as its investments, especially equities, were affected by the global economic uncertainty.
The EPF said in a statement yesterday income from equities in the June to September period fell by more than half to RM1.26bil from RM2.54bil in the preceding quarter.
In line with accounting best practices and as a conservative provisioning policy, the EPF also made allowances amounting to RM2.29bil for diminution in the value of equity investments due to the deterioration in market value compared with RM416.7mil in Q2.
“The outlook in the fourth quarter is likely to reflect the full-scale impact of the global meltdown, although there is still hope for the Malaysian equity market to bounce back,” chief executive officer Datuk Azlan Zainol said yesterday.
Azlan believed Malaysia’s competitive edge would help sustain the economy during these difficult times.
The EPF said due to the current global economic uncertainty, stock markets across the globe had fallen significantly, including the local equity market.
Bursa Malaysia’s market capitalisation during Q3 shrank by about RM200bil to RM770bil.
In the same period, the KL Composite Index fell 243.81 points, or 19.3%, to 1,018.68.
On the investment income of RM2.06bil in Q3, the EPF said it was predominantly driven by Malaysian government securities (MGS) and loans and bonds.
In the quarter under review, the EPF received 3.1% higher returns from loans and bonds, raising income to RM1.71bil which was an increase of 3.14% or RM52.05mil from Q2’s RM1.66bil.
Its investment income in MGS rose 1.38% to RM1.217bil against the preceding quarter’s RM1.2bil.
EPF said the most of Q3 investments were in the trade and services sector and the finance sector comprising 38% and 33.9% of total equity investments respectively.
The next largest Q3 equity investment was in the plantations sector, representing 8.5% of total equity investments.
Money market instruments provided an income of RM142.25mil, down 49.21% from RM191.46mil in Q2.
Investments in properties yielded returns of RM21.53mil, down from RM22.66mil in Q2.
“The EPF will always maintain a policy of low-risk investment decisions. As a national premier pension fund, we cannot afford to take on high risk investments,” Azlan said.
Wednesday, December 3, 2008
Actuarial and Financial Mathematics Seminar at USIM
The Faculty of Science and Technology at University Sains Islam Malaysia (USIM) will be holding a seminar in Actuarial Science and Financial mathematics on 12 January 2008. One of the presenters will be Prof. Dr. Jeyaraj Vadiveloo who is a Watson Wyatt Professor at The University of Connecticut, Storrs, USA.
This seminar is being organized by the final year students of the BSc Honours in Actuarial Science program at USIM.
This seminar is being organized by the final year students of the BSc Honours in Actuarial Science program at USIM.
EPF better than stock Market?
See if this article from The Star makes any sense to you.
Wednesday December 3, 2008
EPF better than stock market
It never gives negative returns
IN general, most people have the impression that the money placed in the Employees Provident Fund (EPF) always generates lower returns compared with the returns from their own investments.
In this article, we will look into the returns from EPF versus returns from the KL Composite Index (KLCI). We assume that investors are able to generate their own returns equivalent to the returns from the KLCI.
Based on our 23 years of data compilation, it is generally true that the average returns generated from EPF are lower than KLCI returns. From 1986 to 2008, the average return of EPF was 6.7%, 2.3 percentage points lower than the average return of 9% from the KLCI (see table).
However, most people do not understand the risks they need to undertake when they invest by themselves. The standard deviation of EPF is only 1.5%, 22.2 percentage points lower than the standard deviation of 23.7% from the KLCI.
We use standard deviation to measure risks. Most investors only look at how to generate the extra 2.3 percentage point returns, forgetting that they need to undertake a much higher risk to generate the extra returns. The extra return is unable to compensate for the extra risks that investors need to take.
Let’s assume one investor invested RM10,000 in the EPF and the KLCI respectively at the beginning of 1986. Logically with the average KLCI return higher than the average EPF return, the fund in KLCI should be higher than the fund in EPF in most periods.
However, as the table shows, by the end of 2008 (we assume that EPF will only be able to generate a return of 4.25%), the fund placed in KLCI would have reached RM40,000 versus RM43,946 generated by EPF, a shortfall of RM3,946.
The main reason behind this shortfall is that the EPF never gives negative returns whereas the KLCI generated negative returns eight times over the past 23 years.
There is a market saying that out of 10 people who invest in the stock market, only one can make money, the others will lose money. Warren Buffett says if you want to win, you don’t lose. Hence, we disagree with some people who advise others not to place money in EPF because it generates lower returns.
In most periods, the money in EPF gets lower return than the money placed in KLCI. However, the main reason for the lower fund value in KLCI by the end of 2008 was the market crash during 1998.
The money in KLCI dropped by 47.1% to RM18,105 in 1998 from RM34,246 in 1997 whereas the money placed in EPF increased further to RM26,594 in 1998 from RM24,924 in 1997. After 1998, it took nine years for KLCI to catch up with the fund value in EPF.
Last year the fund value in KLCI (RM46,000) finally surpassed the fund value in EPF (RM42,154). However, as a result of the recent market crashes, we are anticipating the fund value in EPF to overtake KLCI again this year.
It will take a few years from now for the KLCI to catch up with the EPF again. Unless investors are constantly monitoring their own investments and are able to avoid most of the negative returns, we think it is safer to put money in the EPF rather than withdraw it for their own investments.
Wednesday December 3, 2008
EPF better than stock market
It never gives negative returns
IN general, most people have the impression that the money placed in the Employees Provident Fund (EPF) always generates lower returns compared with the returns from their own investments.
In this article, we will look into the returns from EPF versus returns from the KL Composite Index (KLCI). We assume that investors are able to generate their own returns equivalent to the returns from the KLCI.
Based on our 23 years of data compilation, it is generally true that the average returns generated from EPF are lower than KLCI returns. From 1986 to 2008, the average return of EPF was 6.7%, 2.3 percentage points lower than the average return of 9% from the KLCI (see table).
However, most people do not understand the risks they need to undertake when they invest by themselves. The standard deviation of EPF is only 1.5%, 22.2 percentage points lower than the standard deviation of 23.7% from the KLCI.
We use standard deviation to measure risks. Most investors only look at how to generate the extra 2.3 percentage point returns, forgetting that they need to undertake a much higher risk to generate the extra returns. The extra return is unable to compensate for the extra risks that investors need to take.
Let’s assume one investor invested RM10,000 in the EPF and the KLCI respectively at the beginning of 1986. Logically with the average KLCI return higher than the average EPF return, the fund in KLCI should be higher than the fund in EPF in most periods.
However, as the table shows, by the end of 2008 (we assume that EPF will only be able to generate a return of 4.25%), the fund placed in KLCI would have reached RM40,000 versus RM43,946 generated by EPF, a shortfall of RM3,946.
The main reason behind this shortfall is that the EPF never gives negative returns whereas the KLCI generated negative returns eight times over the past 23 years.
There is a market saying that out of 10 people who invest in the stock market, only one can make money, the others will lose money. Warren Buffett says if you want to win, you don’t lose. Hence, we disagree with some people who advise others not to place money in EPF because it generates lower returns.
In most periods, the money in EPF gets lower return than the money placed in KLCI. However, the main reason for the lower fund value in KLCI by the end of 2008 was the market crash during 1998.
The money in KLCI dropped by 47.1% to RM18,105 in 1998 from RM34,246 in 1997 whereas the money placed in EPF increased further to RM26,594 in 1998 from RM24,924 in 1997. After 1998, it took nine years for KLCI to catch up with the fund value in EPF.
Last year the fund value in KLCI (RM46,000) finally surpassed the fund value in EPF (RM42,154). However, as a result of the recent market crashes, we are anticipating the fund value in EPF to overtake KLCI again this year.
It will take a few years from now for the KLCI to catch up with the EPF again. Unless investors are constantly monitoring their own investments and are able to avoid most of the negative returns, we think it is safer to put money in the EPF rather than withdraw it for their own investments.
Friday, November 28, 2008
Government Pension Scheme
Friday November 28, 2008
Pak Lah: Civil servants can go back to pension scheme
By SIM LEOI LEOI
PUTRAJAYA: Some 40,000 civil servants, who had opted for the Employees Provident Fund, can now revert to the pension scheme.
Prime Minister Datuk Seri Abdullah Ahmad Badawi said these civil servants can exercise their option to revert to the pension scheme in January.
“Their decision will take effect from Feb 1, and they will be able to enjoy all the facilities currently entitled to pensioners, such as free medical treatment. Parents of civil servants, who have passed away and were single at that time, will also receive ex-gratia payments.
“These are some of the decisions that were made following a recent meeting by the Cabinet committee on appointments and salaries for civil servants,” he said in his speech before presenting the Public Sector Quality Awards at the Putrajaya International Convention Centre here yesterday.
Other decisions taken by the committee included upgrading the salary schemes for investigating officers under the Anti-Corruption Agency and for senior, low-ranking officers and constables in the police force, and a 20% increase in pay for maritime officers.
“All these decisions will be effective from Jan 1,” he said, adding that the Government would work out the actual amount of financial allocation involved in the upgrading and salary increase later.
Cuepacs welcomed the move to allow civil servants on the EPF scheme to opt for the pension scheme, said its secretary-general Ahmad Shah Mohamad Zain.
Last week, Cuepacs president Omar Osman complained that civil servants who opted for EPF scheme did not enjoy benefits such as free medical treatment in government hospitals and gratuity payments upon their retirement.
The Star
The reason for allowing civil servants to choose the EPF sccheme was to reduce the government's long term liability for future pension payments. Now that all the civil servants who chose to be in the EPF scheme are allowed to go back to the pension scheme, has there been any calculation on how much more the government need to pay for the pensions? There should be some figures given on the long term liabilities calculated by qualified actuaries.
The idea of allowing civil servants to opt for the EPF scheme has many advantages. It allows for freer movements of civil servants to the private sector. It also protects civil servants who might run foul of the law and get their pensions cancelled. The retirees also will get one lump sum payment on retirement and if the money is managed properly will result in a prosperous retirement.
The disadvantages of the EPF scheme could be easily overcome to allow the civil servants who choose the EPF scheme to enjoy similar benefits to those who choose the pension scheme. The same medical benefits and other related benefits given to those who choose the pension scheme could be given to those who choose the EPF scheme.
The amount of money withdrawn at retirement could be increased if the contribution of the government to EPF for each employee could be increased from the current 12% to 17.5%. This would not increase the government's expenses because, as it is, the government has to contribute an amount equal to 17.5% of each employee's salary to the Kumpulan Wang Amanah Pencen for every employee who choose the pension scheme.
Pak Lah: Civil servants can go back to pension scheme
By SIM LEOI LEOI
PUTRAJAYA: Some 40,000 civil servants, who had opted for the Employees Provident Fund, can now revert to the pension scheme.
Prime Minister Datuk Seri Abdullah Ahmad Badawi said these civil servants can exercise their option to revert to the pension scheme in January.
“Their decision will take effect from Feb 1, and they will be able to enjoy all the facilities currently entitled to pensioners, such as free medical treatment. Parents of civil servants, who have passed away and were single at that time, will also receive ex-gratia payments.
“These are some of the decisions that were made following a recent meeting by the Cabinet committee on appointments and salaries for civil servants,” he said in his speech before presenting the Public Sector Quality Awards at the Putrajaya International Convention Centre here yesterday.
Other decisions taken by the committee included upgrading the salary schemes for investigating officers under the Anti-Corruption Agency and for senior, low-ranking officers and constables in the police force, and a 20% increase in pay for maritime officers.
“All these decisions will be effective from Jan 1,” he said, adding that the Government would work out the actual amount of financial allocation involved in the upgrading and salary increase later.
Cuepacs welcomed the move to allow civil servants on the EPF scheme to opt for the pension scheme, said its secretary-general Ahmad Shah Mohamad Zain.
Last week, Cuepacs president Omar Osman complained that civil servants who opted for EPF scheme did not enjoy benefits such as free medical treatment in government hospitals and gratuity payments upon their retirement.
The Star
The reason for allowing civil servants to choose the EPF sccheme was to reduce the government's long term liability for future pension payments. Now that all the civil servants who chose to be in the EPF scheme are allowed to go back to the pension scheme, has there been any calculation on how much more the government need to pay for the pensions? There should be some figures given on the long term liabilities calculated by qualified actuaries.
The idea of allowing civil servants to opt for the EPF scheme has many advantages. It allows for freer movements of civil servants to the private sector. It also protects civil servants who might run foul of the law and get their pensions cancelled. The retirees also will get one lump sum payment on retirement and if the money is managed properly will result in a prosperous retirement.
The disadvantages of the EPF scheme could be easily overcome to allow the civil servants who choose the EPF scheme to enjoy similar benefits to those who choose the pension scheme. The same medical benefits and other related benefits given to those who choose the pension scheme could be given to those who choose the EPF scheme.
The amount of money withdrawn at retirement could be increased if the contribution of the government to EPF for each employee could be increased from the current 12% to 17.5%. This would not increase the government's expenses because, as it is, the government has to contribute an amount equal to 17.5% of each employee's salary to the Kumpulan Wang Amanah Pencen for every employee who choose the pension scheme.
Tuesday, October 28, 2008
Muslim Gold Standard
http://www.worldfutures.info/Analysis/Islamic-World/Islamic-World-Wither-a-Muslim-Gold-Standard.html
Islamic World: Wither a Muslim Gold Standard?
Written by Kazi Mahmood
Saturday, 25 October 2008
The last few times we heard of the Muslim world using Gold to replace currency was during the time of Prime Minister Tun Mahathir's reign. He was sure and certain that Gold cold bring the downfall of the paper money era.
Since then, the idea fizzled amid a few attempts at promoting Gold itself as a currency and as a means to make payments internationally. The business of gold minting in Malaysia, which started with a few companies minting gold for sale locally, went bust.
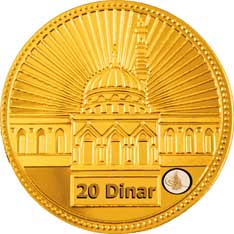
A type of Gold Dinar from UK
One wonders how doing business with gold can go bust but it is a reality in Malaysia since the people involved in the business were after the quick profit, not after the long haul of becoming rich and solid after years of patience and perseverance.
Though it is relevant to sell gold coins, it must be done with much publicity and the right approach. Trying to impose gold as the currency to be carried around does not work in the modern age. People need cards, gold cards that can help carry thousands of dollars around like in credit cards. We are in the age of the digital money too, and the gold coins providers could shift their businesses more into the cyberspace.
Now what about the gold as Islamic currency?
During that period, writing for Islamonline.net, I suggested that we use gold as the standard, not as the currency necessarily and that this will mean backing the currency we use with pure, existing gold stocks. This idea did not take up since it does not bring ready, quick bucks to any of the would be investors in this business.
Now let me tell you about the US. The much hated and much criticized US governments over the years did one right thing. They used gold as the standard and created a unique type of gold currency investment.
This gold currency investment sores in price after gold prices rise. The profit can be huge and dramatically turn the investments into windfall gains, unexpected and much wanted.
How do they do it?
Everybody knows that gold is a safe investment in times of economic chaos--that's why the U.S. mint recently ran out of gold bullion coins to sell to investors (source: The Los Angeles Times).
The US print money, paper money, to pay for its follies and yet the more it prints, the better it is for Gold prices. In that case, you do not need to own gold itself to earn the benefits of the current US policies. What you need is follow the price of gold on the market and invest in gold currencies that exists for decades in the US.
What about the Islamic world?
What the Mahathir followers in the gold coins business failed to understand is how to use a gold standard system to back the Muslim world's currencies. What the US did was to back their currency with gold standards = the US remains one of the major gold hoarding nations on earth.
Simply follow the US principle and integrate gold in the modern currency system by backing one's entire currencies on gold would have created support for gold currency standards but no one will do that since there is no 'profit' to be made by 'brokers'. That is the real problem faced in the Muslim world and it has escaped the promoters of gold currencies in countries like Malaysia.
The question is will there be a gold standard for the Muslim world? There can be such a standard only if the Arab world with the Asians and Africans in the Organization of Islamic Conference (OIC) pushes for gold to become the standard currency to be used to back the existing paper money.
Its a long shot and it may not see the light not with this generation of Muslims anyway.
Islamic World: Wither a Muslim Gold Standard?
Written by Kazi Mahmood
Saturday, 25 October 2008
The last few times we heard of the Muslim world using Gold to replace currency was during the time of Prime Minister Tun Mahathir's reign. He was sure and certain that Gold cold bring the downfall of the paper money era.
Since then, the idea fizzled amid a few attempts at promoting Gold itself as a currency and as a means to make payments internationally. The business of gold minting in Malaysia, which started with a few companies minting gold for sale locally, went bust.
A type of Gold Dinar from UK
One wonders how doing business with gold can go bust but it is a reality in Malaysia since the people involved in the business were after the quick profit, not after the long haul of becoming rich and solid after years of patience and perseverance.
Though it is relevant to sell gold coins, it must be done with much publicity and the right approach. Trying to impose gold as the currency to be carried around does not work in the modern age. People need cards, gold cards that can help carry thousands of dollars around like in credit cards. We are in the age of the digital money too, and the gold coins providers could shift their businesses more into the cyberspace.
Now what about the gold as Islamic currency?
During that period, writing for Islamonline.net, I suggested that we use gold as the standard, not as the currency necessarily and that this will mean backing the currency we use with pure, existing gold stocks. This idea did not take up since it does not bring ready, quick bucks to any of the would be investors in this business.
Now let me tell you about the US. The much hated and much criticized US governments over the years did one right thing. They used gold as the standard and created a unique type of gold currency investment.
This gold currency investment sores in price after gold prices rise. The profit can be huge and dramatically turn the investments into windfall gains, unexpected and much wanted.
How do they do it?
Everybody knows that gold is a safe investment in times of economic chaos--that's why the U.S. mint recently ran out of gold bullion coins to sell to investors (source: The Los Angeles Times).
The US print money, paper money, to pay for its follies and yet the more it prints, the better it is for Gold prices. In that case, you do not need to own gold itself to earn the benefits of the current US policies. What you need is follow the price of gold on the market and invest in gold currencies that exists for decades in the US.
What about the Islamic world?
What the Mahathir followers in the gold coins business failed to understand is how to use a gold standard system to back the Muslim world's currencies. What the US did was to back their currency with gold standards = the US remains one of the major gold hoarding nations on earth.
Simply follow the US principle and integrate gold in the modern currency system by backing one's entire currencies on gold would have created support for gold currency standards but no one will do that since there is no 'profit' to be made by 'brokers'. That is the real problem faced in the Muslim world and it has escaped the promoters of gold currencies in countries like Malaysia.
The question is will there be a gold standard for the Muslim world? There can be such a standard only if the Arab world with the Asians and Africans in the Organization of Islamic Conference (OIC) pushes for gold to become the standard currency to be used to back the existing paper money.
Its a long shot and it may not see the light not with this generation of Muslims anyway.
Monday, October 6, 2008
BBA Financing
Wednesday, September 10, 2008
BBA: Banking sector braces for impact from ruling
By HABHAJAN SINGH
The Islamic banking fraternity is bracing to face a fallout from the recent High Court rulling that the application of the Al-Bai' Bithaman Ajil (BBA), a widely used Islamic home financing contract, is contrary to the Islamic Banking Act 1983.
At the heart of the written judgement by Datuk Justice Abdul Wahab Patail is that since some BBA contracts were structurally faulty, defaulters need not pay more than the original financing amount that they received, depriving banks of the profit that they would have otherwise booked from the transaction.
Bankers also fear the judgement could mean that current BBA financing clients would only need to pay the facility amount and would escape from paying the profit portion.
The home financing facilty extended under the BBA concept runs into billions of ringgit. "It will impact (the industry) in a big way. Bankers and financiers are used to the idea that when a default takes place, they are entitled to recover the full balance of the sales price. This and the previous judgement by Justice Wahab has altered that," said a local lawyer who ranks among the pioneers in the field of Islamic finance.
Wahab's latest judgement, dated July 18, encompassed 11 separate cases involving Bank Islam Malaysia Bhd and Arab-Malaysian Finance Bhd as the plantiffs.
It is understood that the banks are appealing to the Court of Appeal to overturn the judgement which was received by lawyers involved in the case only last month.
Industry experts estimate that close to 70% of Islamic financing has been granted under the BBA concept which essentially is a deferred payment sale (the sale of goods on a deferred payment basis) at an agreed selling price, which includes a profit margin agreed on by the customer and the bank.
The BBA concept is widely used in various Islamic financing instruments, including for bridging finance, cash line facilities, contract financing, project financing and letters of credit.
Among the big local players on this front are CIMB Bank Bhd, Malayan Banking Bhd, Bank Islam Malaysia Bhd and Public Bank Bhd, all of whom have home financing facilities based on the BBA concept. Local banks like CIMB and Maybank now have full-fledged Islamic subsidiaries that handle such financing.
"Banks are worried this judgement will set off alarm bells with regard to confidence with BBA locally. As for foreign investors, they fear its potential ramification on Malaysia's efforts in becoming a global hub for Islamic finance.
"Our whole industry has been BBA-driven. Banks are fervently trying to find a solution," said an industry executive.
It is understood that the legal departments of some these banks are now trying to get their hands on Abdul Wahab's latest judgement which has yet to be published by any of the local regular sources for the legal fraternity.
On Monday, The Malaysian Reserve ran a report on Abdul Wahab's ruling followed by excerpts from the 54-page judgement the next day.
The judgement on the appplication of BBA, popular at home but much criticised abroad, is set to be another widely discussed judgement after Abdul Wahab's earlier ruling in the case of Affin Bank Bhd vs Zulkifli Abdullah, in which he passed a ruling on the calculation of the amount to be paid in the event of a foreclosure.
The 2006 case attracted much attention, and is still the subject of seminars today, as it turned on its head the way bank practitioners calculated the outstanding amount to be repaid by borrowers who had defaulted on their BBA contracts.
Some banks had calculated the amount up to the full period of the facility, even though the borrowers may have defaulted only a few years into the financing. to be fair, though, banks usually have a defaulter rebate, which is at their sole discretion.
"The effect of this judgement is that customers are obliged to pay only the principle that had been extended to them.
"Since the court holds this contract null and void, Section 66 of the Contract Act will apply," said a lawyer. Section 66 of the act states that "when an agreement is discovered to be void, or when a contract becomes void, any person who has received any advantage under the agreement or contract is bound to restore it, or to make compensation for it, to the person from whom he received it."
(The Malaysian Reserve, Sept 11, 2008)
Posted by HABHAJAN SINGH at Wednesday, September 10, 2008
Labels: Bank Islam, BBA, Islamic finance, judiciary
BBA: Banking sector braces for impact from ruling
By HABHAJAN SINGH
The Islamic banking fraternity is bracing to face a fallout from the recent High Court rulling that the application of the Al-Bai' Bithaman Ajil (BBA), a widely used Islamic home financing contract, is contrary to the Islamic Banking Act 1983.
At the heart of the written judgement by Datuk Justice Abdul Wahab Patail is that since some BBA contracts were structurally faulty, defaulters need not pay more than the original financing amount that they received, depriving banks of the profit that they would have otherwise booked from the transaction.
Bankers also fear the judgement could mean that current BBA financing clients would only need to pay the facility amount and would escape from paying the profit portion.
The home financing facilty extended under the BBA concept runs into billions of ringgit. "It will impact (the industry) in a big way. Bankers and financiers are used to the idea that when a default takes place, they are entitled to recover the full balance of the sales price. This and the previous judgement by Justice Wahab has altered that," said a local lawyer who ranks among the pioneers in the field of Islamic finance.
Wahab's latest judgement, dated July 18, encompassed 11 separate cases involving Bank Islam Malaysia Bhd and Arab-Malaysian Finance Bhd as the plantiffs.
It is understood that the banks are appealing to the Court of Appeal to overturn the judgement which was received by lawyers involved in the case only last month.
Industry experts estimate that close to 70% of Islamic financing has been granted under the BBA concept which essentially is a deferred payment sale (the sale of goods on a deferred payment basis) at an agreed selling price, which includes a profit margin agreed on by the customer and the bank.
The BBA concept is widely used in various Islamic financing instruments, including for bridging finance, cash line facilities, contract financing, project financing and letters of credit.
Among the big local players on this front are CIMB Bank Bhd, Malayan Banking Bhd, Bank Islam Malaysia Bhd and Public Bank Bhd, all of whom have home financing facilities based on the BBA concept. Local banks like CIMB and Maybank now have full-fledged Islamic subsidiaries that handle such financing.
"Banks are worried this judgement will set off alarm bells with regard to confidence with BBA locally. As for foreign investors, they fear its potential ramification on Malaysia's efforts in becoming a global hub for Islamic finance.
"Our whole industry has been BBA-driven. Banks are fervently trying to find a solution," said an industry executive.
It is understood that the legal departments of some these banks are now trying to get their hands on Abdul Wahab's latest judgement which has yet to be published by any of the local regular sources for the legal fraternity.
On Monday, The Malaysian Reserve ran a report on Abdul Wahab's ruling followed by excerpts from the 54-page judgement the next day.
The judgement on the appplication of BBA, popular at home but much criticised abroad, is set to be another widely discussed judgement after Abdul Wahab's earlier ruling in the case of Affin Bank Bhd vs Zulkifli Abdullah, in which he passed a ruling on the calculation of the amount to be paid in the event of a foreclosure.
The 2006 case attracted much attention, and is still the subject of seminars today, as it turned on its head the way bank practitioners calculated the outstanding amount to be repaid by borrowers who had defaulted on their BBA contracts.
Some banks had calculated the amount up to the full period of the facility, even though the borrowers may have defaulted only a few years into the financing. to be fair, though, banks usually have a defaulter rebate, which is at their sole discretion.
"The effect of this judgement is that customers are obliged to pay only the principle that had been extended to them.
"Since the court holds this contract null and void, Section 66 of the Contract Act will apply," said a lawyer. Section 66 of the act states that "when an agreement is discovered to be void, or when a contract becomes void, any person who has received any advantage under the agreement or contract is bound to restore it, or to make compensation for it, to the person from whom he received it."
(The Malaysian Reserve, Sept 11, 2008)
Posted by HABHAJAN SINGH at Wednesday, September 10, 2008
Labels: Bank Islam, BBA, Islamic finance, judiciary
Subscribe to:
Posts (Atom)
